


Why the Cheapest Car Insurance Premium Often Costs More
This year, Ramesh may end up spending ₹2.4 lakh in repairs out of his pocket, even though he has OD car insurance with the cheapest premium plan of ₹8,500. But his new insurance advisor saves him that repair cost with a new plan that costs just ₹3,000 more.
Most car owners want to reduce their insurance premium, but because of that many fall into the trap of choosing one with lower overall value or coverage. The issue arises from using only the premium price as the deciding factor. It overlooks various hidden details that determine the actual payout of a claim.
The key to smart insurance isn't the cheapest plan, but it’s finding the best value by comparing coverage, policy and payout conditions, Exclusions, Insured Declared Value (IDV), deductibles both mandatory and voluntary, and various add-ons.
An average person may feel overwhelmed and confused when analyzing so many factors, and end up delaying the necessary insurance cover that can cost them lakhs someday.
Ramesh faced the same dilemma when he sat down to figure out a better car insurance plan for himself. His previous purchases were all low-priced policies, and were all based on misconceptions that ultimately cost him more during claims. He was frustrated by the sheer volume of details to analyze in a policy.
So, Ramesh tried a new insurance advisor, who presented him with three policies.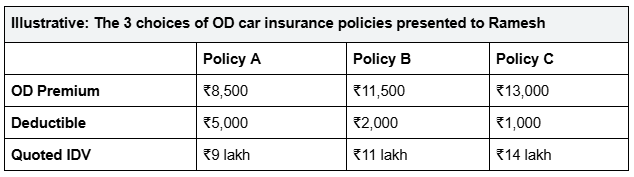
The advisor then clarified that the assessment can be made simpler by focusing on the insured perils coverage, the insured declared value (IDV) limit, the voluntary deductibles, and the add-ons needed outside the base cover. The difference between differently priced plans often boils down to the fine print under these policy clauses.
On Ramesh’s request, his insurance advisor sat down to help navigate him through his existing misconceptions and guide him towards a better choice.
Misconception 1: “The Cheapest Plan Covers all Core Risks, Same as all other Plans”
Almost all OD car insurance policies cover damages caused by these 5 perils: accident, theft, fire, natural calamities like floods, and man-made events like riots.
Cheaper plans also cover the same, but they can differ in the coverage conditions, claim payout conditions, exclusions, and consequences of non-compliance. This crucial difference in the details can mean a peril is covered, but the specific claim conditions may make the payout inadmissible.
After buying policy A, Ramesh gets into an accident with a total bill of ₹2.4 lakh. He knows his accident is covered and assumes that his repair bill will be taken care of by insurance.
But he fails to inform the insurance company within 24 hours, as per the claim payout requirement of policy A. His claim gets rejected even though the accident event that caused the damage was covered. The costlier policies B or C, offering a more reasonable claim window of 3 and 7 days respectively, seemed like better choices to him at this moment.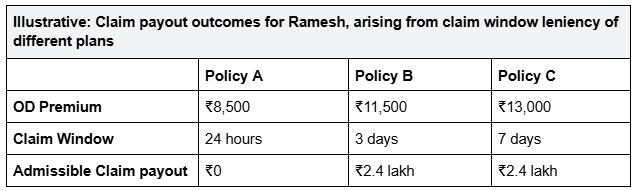
By choosing policy A, he saves ₹3,000 in premiums compared to the next-priced plan, but its inadequate claim window conditions led to a rejection of his insurance claim and cost him the complete repair bill of ₹2.4 lakh that year. Policies B or C with more lenient claim windows would have saved Ramesh from the ₹2.4 lakh bill.
Misconception 2: “The IDV Limit of the Cheapest Plan will be Enough for me”
If the same accident had caused irreparable damage to Ramesh’s car, then he would have to file a total-loss claim. The maximum admissible payout in this claim situation depends on the quoted IDV provided by the insurance company. Insurance companies release the exact computation method for their IDVs.
But the payout actually needed by the policy buyer can be estimated from a benchmark IDV using the manufacturer’s current listed selling price for the make, model, and variant, and then depreciated according to the age of the car. This benchmark can be compared to the policy quoted IDV values to arrive at the plan choices with appropriate coverage. The benchmark IDV must have the same computation method as the insurance IDV.
Benchmark IDV = Manufacturer's Current Listed Price × (1 − Depreciation Rate)
Ramesh had bought his car for ₹12 lakh, and its current listed price is ₹13 lakh. According to the insurance company’s policy wording, his 1-year-old car is depreciated by 20%.
Benchmark IDV for Ramesh’s car = ₹13 lakh × (1 − 0.20) = ₹10.4 lakh
This is the benchmark that Ramesh can compare against all policy-quoted IDV values.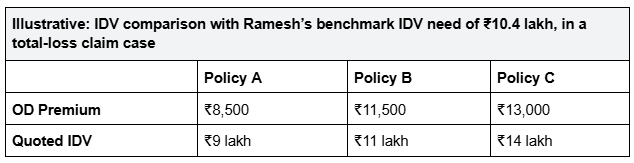
Policy A offers an IDV that is ₹1.4 lakh less than the benchmark of ₹10.4 lakh, even though it saves a premium of ₹3,000. Policy B offers an IDV that covers the benchmark. Policy C offers an IDV that exceeds the benchmark by ₹3.6 lakh, but costs ₹4,500 more in premiums.
Based on the IDV comparison, Ramesh may want to adequately cover a total-loss-claim and narrow his choices to policies B and C. Ultimately, policy B may be his first choice, but he may want to investigate Policy C for any extra essential benefits that may be contributing to its higher premiums.
Misconception 3: “I don’t need Add-ons. The Cheapest Plan Already Covers all Major Car Damages”
Car Insurance policies offer many add-ons, like Consumable cover, Engine damage cover, and Nil Depreciation benefit, to name a few. Many find them extremely useful and worth the extra premiums.
If Ramesh has an accident with a total repair bill of ₹2.4 lakh, he would file a partial-loss claim. His repair costs are: ₹30,000 to replace plastic parts, ₹60,000 to replace metal parts, ₹80,000 for engine damage from accident-induced oil leakage, ₹20,000 for two damaged tyres, ₹40,000 for labour costs, and ₹10,000 for consumables used during repair.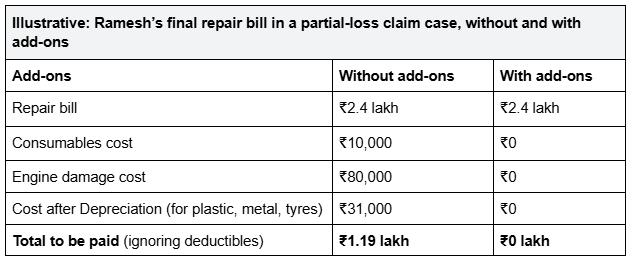
Without any add-ons, Ramesh would have to pay ₹1.19 lakh. By paying an extra premium for the added covers, in the range of a few hundred, he could have saved himself this massive repair bill.
Why SimpliInsure?
Choosing a plan with a low premium is not wrong at all, but Ramesh failed to account for the catastrophic expenses he would have to bear, in the year he filed a claim.
1. Ramesh held the misconception that the cheapest car insurance plan would give complete base coverage.
SimpliInsure’s advisory team would not only help Ramesh choose policies with appropriate coverage but also compare the fine print of his options alongside the coverage conditions and exclusions, so that he is fully informed of what is included in his policy.
2. Ramesh held the misconception that the IDV limit of the cheapest plan would be enough for him.
SimpliInsure’s advisory team would help him calculate his required IDV based on his car and help him choose the limit that actually fits his car’s value.
3. Ramesh held the misconception that since the cheapest plan has own-damage cover, his insurance will pay for all repair bills.
SimpliInsure’s advisory team would show that even though the accident and the damage both are covered by his policy, the claim payouts are calculated using an additional set of rules. They would also show what he would save during claim application with the additional add-ons in place.
What Next?
You just now saw how a ₹3,000 premium savings caused Ramesh a ₹2.4 lakh loss. The only question that remains is, whether you want to compare plans alone, or with someone who knows the fine print.
Call SimpliInsure on +91 95133 55661 /62 /63 /64. In 20 minutes our advisors will show you a side-by-side comparison of your renewal options, with premiums, IDV, coverage, claim conditions, everything. That is what SimpliInsure exists to do.
Disclaimer: This content is for informational purposes only and should not be treated as financial, medical, or insurance advice. Policy terms, exclusions, and benefits vary across insurers. Please review official policy documents and seek professional guidance before making decisions.

 English
 Arabic
 Français
 Español
 Português
 Deutsch
 Türkçe
 Dutch
 Italiano
 Russian
 Romaian
 Greek