
Smart Estate Planning: When a Living Trust Makes Sense
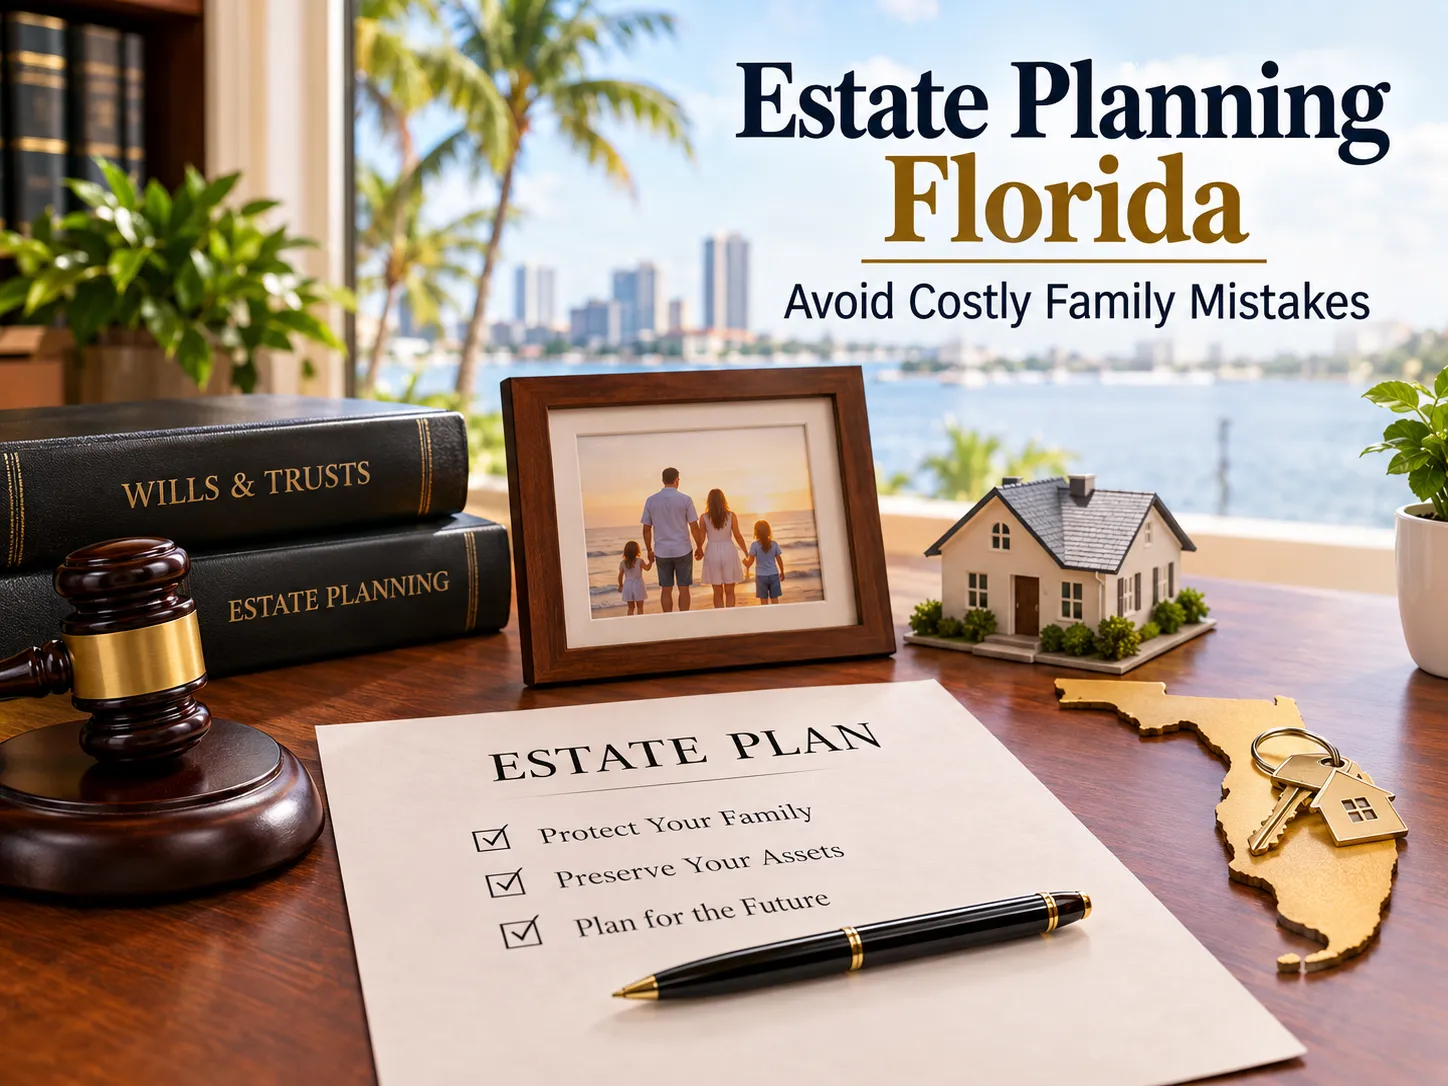
Estate planning is not only about deciding who receives your property after you die. A good plan can also help manage your assets during your lifetime, prepare for unexpected incapacity, and reduce confusion for the people who may need to handle your affairs.
For some families, a trust can be an effective part of that plan. However, a trust is not automatically the right solution for everyone. Understanding how it works, what it can accomplish, and what responsibilities come with it can help you make a more informed decision.
What Is a Living Trust?
A living trust is an estate planning arrangement created while a person is alive. The person who creates the trust is commonly called the grantor or trustmaker. The trust holds assets according to written instructions, while a trustee manages those assets.
In many cases, the person creating the trust initially serves as trustee and maintains control over the property. A successor trustee is named to step in if the original trustee becomes incapacitated or dies.
This arrangement can provide continuity in asset management and give family members clear instructions about what should happen to trust property.
Why Do People Create a Revocable Living Trust?
A revocable living trust is designed to provide flexibility while the creator is alive. Depending on the trust terms and applicable state law, the creator may generally be able to change the trust, amend its instructions, change beneficiaries, or revoke it.
That flexibility can be valuable because family and financial circumstances rarely remain unchanged for decades.
For example, you may purchase a new home, acquire investment property, start a business, get married, experience a divorce, welcome a child, or experience a major change in your finances. An estate plan should be reviewed when these events occur.
Can a Trust Help With Incapacity Planning?
One overlooked part of estate planning is preparing for a period when you cannot manage your own affairs.
An accident, illness, or cognitive decline could make it difficult or impossible to handle financial responsibilities. If assets are appropriately placed in a trust, the successor trustee may be able to manage those trust assets according to the trust's instructions if the original trustee can no longer serve.
This can provide a level of continuity for property management, investment accounts, and other assets included in the trust.
However, a trust is only one part of incapacity planning. Other documents, such as financial powers of attorney and healthcare directives, may also be important depending on individual circumstances.
Does Creating a Trust Automatically Protect Every Asset?
No. One of the most common misunderstandings is assuming that signing trust documents automatically places all property under the trust.
The process of transferring appropriate assets into the trust is often called trust funding. The exact process depends on the type of asset and applicable laws.
For example, real estate may require a properly prepared and recorded deed. Financial accounts may have their own ownership requirements. Retirement accounts and life insurance policies often involve separate beneficiary designations.
This is why creating the document is only part of the estate planning process.
What Assets May Be Included?
The assets that belong in a trust depend on the individual's circumstances and estate planning goals. Common examples may include:
- Residential or investment real estate
- Certain bank accounts
- Investment assets
- Business interests
- Valuable personal property
- Other assets that can appropriately be titled in the trust
Some assets may be handled outside the trust through beneficiary designations or other legal arrangements.
The important goal is coordination. Your trust, will, beneficiary designations, powers of attorney, and healthcare documents should work together rather than create conflicting instructions.
When Should You Work With a Living Trust Attorney?
Online information can help you understand basic estate planning concepts, but every person's situation is different. State laws can also affect how trusts, property, probate, taxes, and beneficiary rights are handled.
A living trust attorney may be particularly helpful when your estate includes multiple properties, business ownership, substantial investments, minor children, a blended family, or complicated beneficiary arrangements.
Professional legal guidance can help identify which documents may be appropriate and explain how ownership and beneficiary decisions could affect your overall plan.
For readers researching their options, professional estate planning guidance can be a useful external resource when evaluating different planning strategies.
Common Mistakes That Can Cause Problems
Creating a trust without understanding how to maintain it can lead to unnecessary complications.
Not Funding the Trust
A person may sign a trust but fail to transfer appropriate assets into it. This can undermine the purpose of the planning strategy.
Ignoring Beneficiary Designations
Retirement accounts, insurance policies, and certain financial accounts can have separate beneficiary instructions. These should be reviewed as part of the broader estate plan.
Choosing an Unprepared Successor Trustee
The successor trustee may have important administrative responsibilities. Choosing someone simply because they are a close relative may not always be the best decision.
Consider the person's reliability, organizational ability, financial judgment, willingness to serve, and relationship with the beneficiaries.
Never Reviewing the Documents
An estate plan can become outdated. Changes in family relationships, property ownership, financial circumstances, and applicable laws may make a periodic review worthwhile.
Living Trust vs. Will
A trust and a will are not necessarily competing alternatives. They can serve different functions and may work together as part of a complete estate plan.
A will can provide instructions for property and other matters after death. A trust can establish rules for managing assets during life and after death, depending on its terms.
A comprehensive estate plan may also include a financial power of attorney, healthcare power of attorney, advance healthcare directive, beneficiary designations, and other documents.
The right combination depends on your personal circumstances and legal needs.
How to Decide Whether a Trust Fits Your Situation
Instead of asking whether everyone should have a trust, consider the specific problems you want your estate plan to solve.
Ask yourself:
- Who should manage my assets if I cannot?
- Who should receive my property after my death?
- Do I own real estate or other significant assets?
- Do I have minor children or complex family relationships?
- Are my beneficiary designations current?
- Have I clearly selected people to make financial and healthcare decisions if necessary?
- Would my family understand what to do if I became incapacitated?
Your answers can help identify gaps that deserve attention.
Keep Your Estate Plan Updated
Estate planning does not end when documents are signed. Major life events should trigger a review.
Consider reviewing your plan after marriage, divorce, the birth or adoption of a child, the death of a beneficiary, a significant property purchase, a major financial change, or a move to another state.
It is also wise to periodically confirm that important assets are properly titled and that beneficiary designations still reflect your wishes.
Final Thoughts
A carefully designed living trust can help address several practical estate planning concerns, including asset management, incapacity planning, and the orderly transfer of certain property. A revocable structure may also provide flexibility when circumstances change.
The key is to look beyond the document itself. Proper funding, beneficiary coordination, successor trustee selection, and regular reviews are all important parts of effective trust planning.

 English
 Arabic
 Français
 Español
 Português
 Deutsch
 Dutch
 Italiano
 Russian
 Romaian
 Portuguese (Brazil)
 Greek